Exemptions, quotas, quantity limits and Duty free
 Goods intended for commercial purposes, including books, pamphlets, and periodicals, are not covered under the definition of baggage.
The duty-free exemption allowance is valid for all travelers and is granted only once per 30-day period.
EXEMPTION FOR ACCOMPANIED BAGGAGE
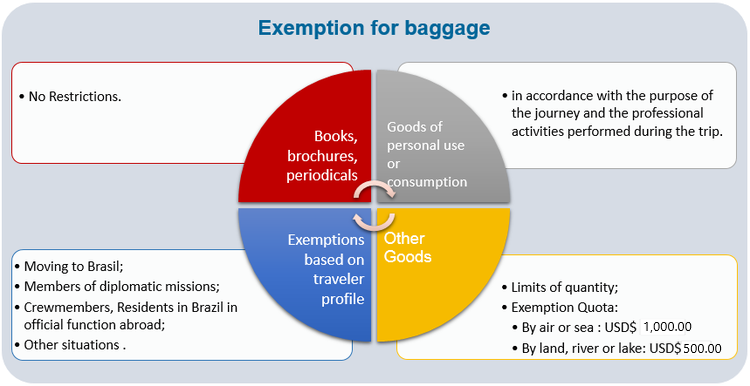
Books, pamphlets, periodicals, and goods for personal use or consumption are exempt from import duties and taxes.
For duty-free exemption purposes, goods for personal use or consumption must cumulatively meet the following conditions:
-
a) The item must be for the traveler's own use;
-
b) The acquisition of the item must have been necessary according to:
-
the circumstances of the trip;
-
the physical condition of the traveler;
-
the professional activities performed during the trip.
-
-
c) The item must be in used condition;
-
d) The nature and quantity of the item must be compatible with the circumstances of the trip.
Exempt goods do not need to be declared, as they are free from import tax collection and are not included in the calculation of the duty-free allowance, unless the traveler wishes to regularize their entry into the country.
Travelers may only bring goods for personal use or consumption; commercial or industrial purposes are strictly prohibited.
EXEMPTION QUOTA FOR ACCOMPANIED BAGGAGE
Goods subject to tax payment that do not qualify as personal use or consumption items under the conditions above will only be exempt if they fall under the definition of accompanied baggage and are within the duty-free allowance limit of US$ 1,000.00 (for arrivals by air or sea) or US$ 500.00 (for arrivals by land, river, or lake).
Import tax exemptions on travelers' baggage are individual and non-transferable; allowances cannot be combined or pooled to benefit from the exemption, even among family members.
Alcoholic beverages, tobacco products, or other products containing ingredients that may cause physical or chemical dependence cannot form part of the baggage of children or adolescents (minors under 18), even when accompanied by their legal representatives.
QUANTITATIVE LIMITS
To enjoy the exemption for accompanied baggage, in addition to the value of quota, it is necessary to pay attention in the following quantity limits:
|
Goods |
Air or Sea Arrivals |
Land, River, or Lake Arrivals |
|
Alcoholic Beverage |
12 liters, in total |
12 liters, in total |
|
Foreign-made cigarretes |
10 packs in total (containing 20 units each) |
10 packs in total (containing 20 units each) |
|
Cigar and Cigarillos |
25 units, in total |
25 units, in total |
|
Tobacco |
250 grams, in total |
250 grams, in total |
|
Other goods |
Under US$ 10.00: up to 20 units, maximum of 10 identical |
Under US$ 5.00: up to 20 units, maximum of 10 identical |
|
Other goods |
Over US$ 10.00: up to 20 units, maximum of 03 identical |
Over US$ 5.00: up to 10 units, maximum of 03 identical |
If quantitative limits are exceeded, provided the quantity does not indicate commercial or industrial intent, the items will still be treated normally as baggage. However, no duty-free exemption will apply to them.
EXEMPTIONS BASED ON TRAVELER PROFILE
Key specificities:
| Traveler Profile | Time of Residence Abroad | Goods Exemption |
| Immigrants or Brazilians returning to the country permanently | More than 1 (one) year - Occasional trips to Brasil do not affect the time count, provided they do not totalize more than 45 days in the previously 12 months from the return to the country. | New or used: furniture and other household goods; and tools, equipaments and instruments necessary for their profession, art or craft. |
| Members of diplomatic missions, consular offices and representatives of international organizations | There is no deadline | Everything, including luggage and cars. |
| Scientists, engineers and technicians, living abroad | There is no deadline, but there are conditions to be observed | New or used: furniture and other household goods; and tools, equipaments and instruments necessary for their profession, art or craft. |
| Residents in Brazil in official function abroad | There is no deadline | Cars, under certain conditions and limitations. |
| Crewmembers | There is no deadline | Only goods for personal use or consumption, books, brochure and periodicals. |
| Crew of long-haul ship when disembark definitively in Brazil | It may be exercised once every one (1) year range. | Everything, respecting the quota limits and tax of 50% on the surplus. |
| Military and civilian on military vehicles | It may be exercised once every one (1) year range. | Everything, respecting the quota limits and tax of 50% on the surplus. |
New items must be accompanied by proof of purchase (receipts/invoices) or justification for their absence; failure to present documentation may trigger special customs audit procedures.
DUTY FREE/FREE SHOP
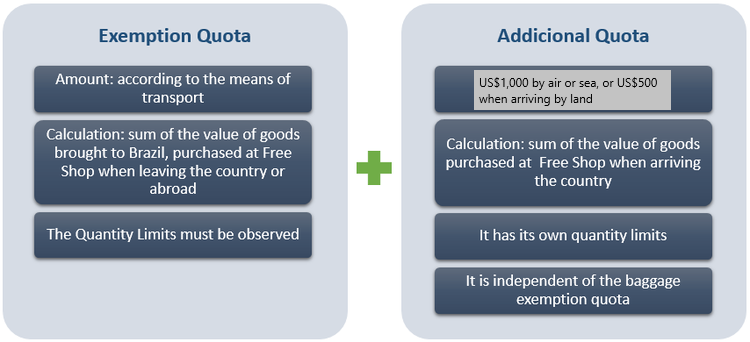
Purchases at Duty Free shops upon departure from Brazil or abroad can be absorbed by the general baggage allowance. Upon arrival in Brazil, travelers are entitled to an additional allowance at the arrival Duty Free shop. Note how the allowance works in each case:
PURCHASES AT DEPARTURE FREE SHOPS (BRAZIL OR ABROAD)
If brought into Brazil, goods acquired at the following locations form part of the traveler's regular baggage and count against their standard duty-free allowance:
-
Departure Duty Free shops in Brazil or abroad;
-
Duty Free shops, catalogs, and displays aboard buses, aircraft, or passenger vessels.
PURCHASES AT ARRIVAL FREE SHOPS IN BRAZIL
-
Travelers are entitled to an additional duty-free allowance of US$ 1,000.00 for purchases made at Duty Free shops located at the first airport of arrival in Brazil.
-
Travelers are entitled to an additional duty-free allowance of US$ 500.00 every 30 days (calculated on a rolling window basis) for purchases at land border Duty Free stores (Lojas Francas).
Any amount exceeding this additional exemption allowance will be taxed under the Simplified Taxation Regime (RTE).
Minors under 18 (eighteen) years of age may not purchase alcoholic beverages or tobacco products, even when accompanied.
QUANTITATIVE LIMITS FOR THE ADDITIONAL DUTY-FREE ALLOWANCE
Purchases made at arrival Duty Free shops in Brazil are subject to the following quantitative limits:
-
Alcoholic beverages:
-
Land border stores: 12 (twelve) liters of alcoholic beverages; and
-
Seaports or airports: 24 (twenty-four) units of alcoholic beverages, observing a maximum limit of 12 (twelve) units per type of beverage;
-
-
Cigarettes: 20 (twenty) packs;
-
Cigars or cigarillos: 25 (twenty-five) units;
-
Pipe tobacco: 250 g (two hundred and fifty grams) of prepared pipe tobacco.
ASSOCIATED LEGISLATION
Portaria do MF nº 112, de 2008
Portaria do MF nº 440, de 2010