Goods to Declare, Tax Calculation and Payment
The traveler who has goods to declare must fill the Electronic Declaration of Travelers Goods (e-DBV). Upon arrival in Brazil, the traveler must choose one of the channels: "Nothing to Declare (Green)" or "Goods to Declare (Red)".
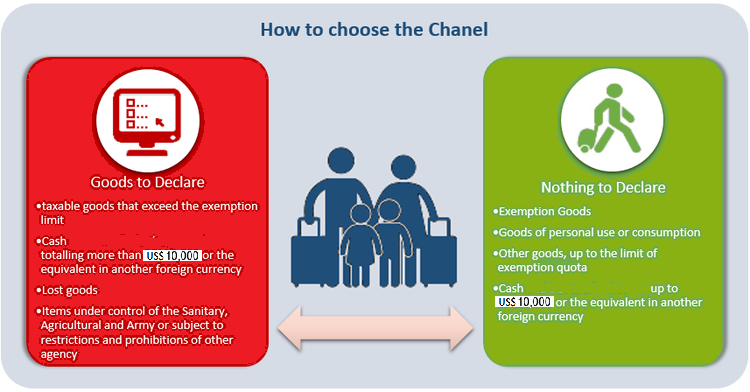
Where there is no “Goods to Declare” channel, the traveler must go to the customs supervision and submit their Electronic Declaration of Travelers Goods (e-DBV) before starting any inspection procedure.
NOTHING TO DECLARE
This channel should be chosen if the the traveler fits in one of the exemption cases.
If the traveler go to “Nothing to Declare” channel and is carrying goods which should have been declared, this option configures misrepresentation and loss of spontaneity to collect the tax due, punishable by a fine of 50% of the amount over the limit of exemption for the transport pathway used.
GOODS TO DECLARE
This channel should be chosen if the traveler has:
 Goods which the overall value exceeds the exemption quota;
Lost goods;
Cash when totalling more than US$ 10,000.00 or the equivalent in another currency, both at the exit of Brazil and upon arrival in the country;
Items under control by Health Dpt, Agricultural Dept and Army or subject to restrictions and prohibitions of other agency;
Items whose entry into the country the traveller wants to prove;
Goods that can not be considered as baggage (goods not included in the baggage concept) such as:
- Vehicles, motorcycles, scooters, motor with bikes, jet skis and similar, as well as their parts and accessories, engines and parts for ship and aircraft;
- Products under health surveillance for the provision of services to third parties;
- Goods that exceed the quantity limits;
- Goods for corporations for subsequent order in the Common Import Regime - RCI;
- Goods that the value exceed US$ 3,000.00 subject to special customs regime of temporary admission, this applies only for non-resident in Brazil.
The Declaration of Travelers Goods of childrens under sixteen (16) years must be made on their behalf by a parent or guardian.
!!!! The following items can not integrate the baggage of children under age, even when accompanied by their legal representatives: alcoholic beverages, tobacco products or other products containing ingredients that can cause physical dependence or chemistry.
SPECIAL TAXATION REGIME (RTE) - CALCULATION OF THE IMPORT TAX
The 50% rate of Import Tax apply on luggage that exceeds the limits of the exemption quota value in compliance with the quantitative limits.
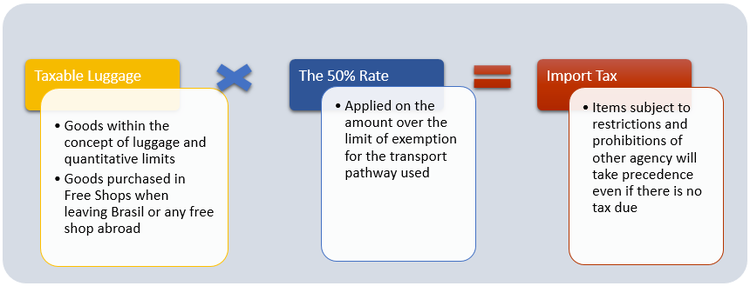
The exchange rate used will be the current on the date of transmission of the Electronic Declaration of Travelers Goods (e-DBV).
The duty-free allowance will be granted only once within any one-month period, counted from the arrival date of the last international trip, regardless of whether duties have been paid.
PAYMENT
- Fill out and transmit the e-DBV and generate the tax payment document
After declaring the goods and providing the requested information, the system will automatically calculate the taxes due, if applicable. Once the declaration transmission is complete, the document for tax payment will be made available. - Check the declaration status
After transmission, the e-DBV will inform whether the traveler is cleared/exempt from presenting themselves or if they must report to customs control.
If the traveler is required to report to customs control, the release of the goods will be conditional upon proof of tax payment. In this scenario, the goods will remain detained by customs until the respective proof of payment is presented, without prejudice to any requirements made by regulatory agencies.
- Make the payment
Payment can be made via DARF (Federal Revenue Collection Document) using a barcoded invoice or PIX (instant payment system).
- Provide proof of payment, when required
When the traveler is required to report to customs control, they must present proof of tax payment so that the goods can be released, provided there are no other restrictions from regulatory agencies. - Release of goods
Goods will be released:
After proof of tax payment is provided, when the traveler is required to report to customs control; or
After compliance with the requirements of other regulatory agencies, when applicable.
In the event that the e-DBV system exempts the traveler from reporting to customs control but the authority requests a physical examination of their baggage and demands tax payment, the goods will only be released after such payment is processed.
THE COMMOM IMPORT REGIME FOR BAGGAGE
The goods brought by travelers which are not in the exemption quota or can not be subject to Special Taxation Regime (RTE), will be subject to the Common Import Regime (RCI).
Goods excluded from the concept of luggage; and
Goods that exceed the quantity limit; and
Goods in unaccompanied baggage that do not reach the country within three months before or six months after the arrival of the traveler; or that are not from the countries of stay or origin of the traveler.
The granting of the Import Regime occurs through the presentation of an Import declaration, formulated in the Integrated Foreign Trade System (SISCOMEX), and must satisfy all the standards for importation.
This procedure is not so simple to be done for people not used to the customs procedures. It is advisable that travelers look for a Customs unit to inquire about the procedures and deadlines.
ASSOCIATED LEGISLATION